Blog
Platform and Industry updates
-
09/16/2026
Structured Filing Data Is More Valuable Than Ever For More Firms
Every year, the Securities and Exchange Commission (SEC) publishes hundreds of thousands – maybe millions, even - of pages of disclosures, filings, amendments and updates across Form ADV, Form D, and many more. The extraordinary amount of information provides remarkable insights into the asset/investment management industry in the USA generally, and on individual investment advisors specifically.
Arguably, no other country provides this level of transparency into this industry (that’s a feature, not a bug). But for firms that rely on regulatory filings to make decisions, generate business opportunities or manage risk, while the availability of data has not been an issue for quite some time, accessing it in a structure that helps provide actionable insights has.
The difference between raw regulatory filings and structured filing data is much the same as the difference between a filing cabinet and a database. Both may contain the same information, but only one enables users to analyze relationships, identify trends and uncover opportunities at scale. That distinction has become increasingly important as investors, managers and service providers seek to make faster and more informed decisions.
Better Data Means Better Investor Protection
The growth in the importance of the operational due diligence function in manager selection in the past decade or so is notable in the US private funds market.
For institutional, sophisticated investors, transparency remains one of the most important foundations of trust. Regulatory filings are intended to provide some of that transparency, but access alone is not enough if critical information remains difficult to analyze and interpret.
Structured filing data helps convert regulatory disclosures into usable intelligence for operational due diligence. Investors and their advisors can more easily assess organizational structures, identify changes in key relationships, such as auditors, and investigate potential risk indicators.
Structured data also allows investors to analyze manager populations at scale. Rather than reviewing filings individually, allocators can compare managers against peer groups, identify outliers and spot changes that may warrant further investigation. For investors monitoring existing manager relationships, this can provide an additional layer of oversight, helping ensure that material organizational changes do not go unnoticed between due diligence cycles.
These features and benefits improve consistency, enhance oversight and support a more informed investment process overall. In an environment like the one today, where governance and risk management receive greater scrutiny, better access to structured regulatory information contributes directly to better investor protections.
Why Investment Managers Care
Investment managers benefit from access to structured data as well.
Competitor intelligence is a clear use case here. Structured datasets help investment management firms analyze trends and shifts in fund structures, observe changes in key service provider relationships within their peer group, and identify emerging areas of market activity.
Structured filing data can also support strategic planning and business development initiatives. Managers can identify which strategies are attracting capital, monitor the launch of competing products and gain a clearer understanding of how peer organizations are evolving. The ability to move beyond anecdotal observations and analyze industry developments through a consistent data set allows firms to make decisions with greater confidence. For smaller and mid-sized managers in particular, access to institutional-quality market intelligence can help level the playing field.
In an industry like alternative investments, where speed and insight create advantages, easier access to competitive intelligence and market trends can materially improve decision-making and outcomes.
We Haven’t Forgotten About Service Providers
For many service providers, integrating a structured filing data solution is an essential component of their go-to-market strategy.
Business development teams can use filing data to identify new market entrants, monitor new fund launches (from both existing managers and new ones) and track which firms are growing assets – including their own clients – and which aren’t. Rather than relying solely on networks or anecdotal market knowledge, they gain access to objective, continuously updated information.
Structured datasets also improve competitor analysis. By tracking relationships between managers, funds and service providers, firms can better understand where competitors are winning mandates, which in turn informs the shaping of their growth strategy.
Because the underlying data is standardized, users can compare organizations consistently across large populations rather than conducting individual reviews on a case-by-case basis. Better information often translates directly into better business development outcomes.
Reading Between the Filings
The volume of regulatory information will continue to increase as AI reduces the barriers to entry for new firms. Automation and advanced analytics will undoubtedly help organizations process that information more effectively.
Yet these technologies all depend on one essential ingredient: high-quality structured data.
Organizations that integrate these tools into their workflows will create significant value for their people, their clients, and their companies and organizations because those users will be able to make better decisions, identify opportunities faster and manage risk more effectively.
Editor's Picks:
Here are a handful of articles that we’ve seen recently that we found interesting. Hopefully, you do, too!
- Equity hedge funds recover, pull back from AI trades in August
- Fitch Ratings’ U.S. Private Credit Default Rate Rose to 6.3% in August 2026
- Rate rise could exacerbate longstanding problems for the US PE industry
- Top 100 infrastructure investors break through the $1trn barrier
- Before The Swan: Why Venture Capital Matters
-
08/18/2026
AI Continues as Dominant Theme in US Private Funds Industry
At the beginning of the year, the savants at JP Morgan Wealth Management offered their thoughts on three themes driving alternatives in 2026: The next phase of artificial intelligence (AI); the quest for portfolio durability; and the evolving liquidity of private markets.
As we approach the home stretch of the year, all three seem to be well-founded, but with the benefit that hindsight brings, some added nuance: AI’s dual-faceted nature of being both an investment opportunity and a source of disruption has become more pronounced; investors have become increasingly selective about where they are willing to take private market risks; and secondary markets have moved further towards the center of the alternatives industry.
AI moves beyond technology
Until recently, much of the investment discussion around AI centered on the companies developing the technology; venture capital funds put more than $250bn, more than half of all VC investments last year, into AI companies.
As the year has progressed, however, the conversation has broadened considerably.
The AI buildout is creating demand for the physical infrastructure required to support it, particularly power, data centers, transmission infrastructure and other forms of real assets. This was one of the areas J.P. Morgan highlighted in January, arguing that constraints around power, energy and other resources could become limiting factors for further AI expansion.
Private infrastructure investors are particularly well positioned to participate here because the capital requirements associated with AI extend well beyond the technology companies themselves; it’s almost as if J.P.Morgan foresaw NVIDIA’s remarkable deal with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to “establish independent financing platforms designed to mobilize over $500 billion of third-party capital to support the buildout of AI infrastructure over time”.
At the same time, the implications of AI have continued to spread into existing alternative investment sectors. Private equity firms are assessing how AI could alter their competitive position, cost structures and growth prospects of portfolio companies, while equity hedge funds in particular have been able to exploit significant dispersion between companies perceived to be AI beneficiaries and those facing disruption (or not).
The bottom line is that for alternative investment fund managers, the question is increasingly not simply whether to invest in AI, but how AI changes the value of businesses, infrastructure and assets across the portfolio, for better or worse.
Selectivity replaces the search for exposure
The second major theme identified by J.P. Morgan has been less about allocating to alternatives in general and more about identifying which of them deserve investor’s capital.
It’s important to point out here that J.P. Morgan’s paper is focused on the wealth management cohort, which has been increasingly turning to alternatives in recent years (institutions, of course, have been allocating heavily for decades).
The firm favoured core private equity, infrastructure, hedge funds and selected areas of credit as potential sources of differentiated returns but cautioned that “Careful manager selection will be critical across the board as dispersion widens.”
The first half of the year shows how difficult that task is. US private equity exits in the second quarter were down almost half, for example. While there are potential reasons – valuations of software portfolio companies during the Covid-19 pandemic being, with the benefit of hindsight, too high, has led to a price divergence between what other sponsors are prepared to pay and what portco owners want to sell at. We would not be surprised to see more continuation vehicles raised in the next 12-18 months as buyout firms look to hold onto assets they consider to be undervalued by the broader market.
And manager selection in private credit and its almost bewildering array of sub-categories has again come to front of mind for investors. The asset class has become an important source of corporate financing, but the rapid growth of the market has also brought greater scrutiny of underwriting standards, portfolio quality, liquidity and the relationship between private credit and the wider financial system.
“Portfolio durability” seems to be less about finding assets that are less correlated with public markets and more about finding managers and strategies capable of navigating a market in which the dispersion between winners and losers is becoming increasingly significant (and will likely continue to do so, thanks, or no thanks, to AI).
Private-market liquidity becomes structural
If there is one area in which the first half of 2026 has arguably exceeded expectations, it is the development of private-market liquidity.
J.P. Morgan identified the growing importance of evergreen funds, continuation vehicles and secondary markets at the beginning of the year. It noted that approximately 20% of alternative assets under supervision in its private bank were already held in evergreen vehicles, while continuation vehicles represented nearly 20% of global private equity exits.
Since then, the secondary market has continued to break records.
Campbell Lutyens 1H 2026 Secondary Market Flash Report estimates that private-market secondary transaction volume reached $120bn in the first half of 2026, putting the market on course for another record year. Lazard's estimate is even higher, putting first-half secondary volume at approximately $124 billion, up 28% year-on-year.
That secondaries have continued to grow in recent years suggests that this corner of the private markets industry is not a tactical asset allocation designed to capture alpha from a difficult exit environment but an asset allocation sleeve in its own right. As funds age, investors need more ways to rebalance portfolios, realise value and manage exposure and continuation vehicles, LP-led transactions, GP-led solutions and evergreen structures are therefore becoming an increasingly permanent part of the private markets architecture, particularly in wealth management, where investors prefer the optionality that open-ended structures offer.
AI is still likely to dominate
You just can’t ignore it. While the exit environment for private equity might be tough at the moment, and private credit might be enduring some teething troubles, while we don’t know the future, cyclicality is a thing, and we have seen this movie before, to a certain extent.
But we haven’t seen the AI one. It’s like we’re in a decade-long Netflix show and we’ve only just finished season one. Some will win, and some will lose, but a year from now, whether it’s us writing a ‘year so far’ article or someone else, we doubt AI will be far from the conversation.
Editor's Picks:
Here are a handful of articles that we’ve seen recently that we found interesting. Hopefully, you do, too!
-
06/15/2026
Why Wall Street Dominates Placement-Agent Rankings — and Why Boutiques Still Matter
Third-party marketers. Placement agents. Whatever term you use for them, 90% of firms don’t list a marketer on their EDGAR filings, clearly preferring to go it alone on the fundraising trail.
But for the 10% that do, plenty of marketing firms are doing something very right, because they help private fund investment managers raise billions of dollars of assets every year across the entire spectrum of asset classes and strategies.
As part of our process here at 9AT, our scouring of the Form ADV and Form D filings shows what would seem to be a huge 2,500 firms receiving a credential as a ‘marketer’ on regulatory filings, good for more than $21.68trn of gross asset value (GAV) in aggregate.
Leading the way are the investment banks. That should not be a surprise, as these firms are often helping to raise capital for the largest, most established alternative asset managers, and those mandates can be enormous. A single assignment for a multi-billion-dollar private equity, infrastructure or private credit fund can have a greater impact on rankings than numerous smaller mandates combined.
Add to that their longstanding relationships with their global network of investors, including pension funds, sovereign wealth funds and insurance companies, and the wider suite of advisory services they offer beyond capital raising, and it makes sense why these firms dominate the leaderboard, as can be seen from Table 1 below.
Table 1: Top 10 Third Party Marketers for Private Investment Funds, by Total Fund GAV*
Firm/Marketer
Total Gross Asset Value
MORGAN STANLEY $ 942,011,984,267 JPMORGAN CHASE $ 933,620,411,662 UBS GROUP $ 915,207,040,644 MIRAE ASSET $ 824,372,342,544 GOLDMAN SACHS $ 582,078,583,510 MITSUBISHI UFJ ALTERNATIVE INVESTMENT CO LTD. $ 446,509,825,782 BANK OF AMERICA $ 444,116,913,829 BARCLAYS $ 396,654,165,981 CITIGROUP $ 359,064,457,932 ICAPITAL $ 259,192,007,320 Source: 9AT
*at June 24th, 2026
This dominance of large investment banks at the top of the rankings raises an obvious question, however: if global banks possess the scale, relationships and resources to lead the market, why do specialist third-party marketers continue to play such a prominent role in private markets fundraising?
The answer lies in a) the diverse needs of fund managers themselves and b) smaller and emerging managers being…too small and emerging for the bulge-bracket firms.
While the largest alternative asset managers may want and need global distribution capabilities, the long tail requires a more targeted, hands-on approach, which creates opportunities for boutique placement agents to carve out valuable niches.
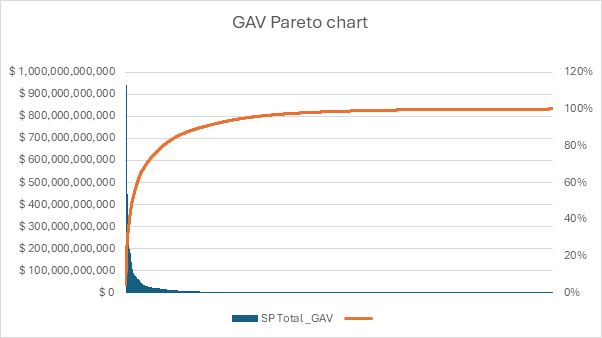
Indeed, the distribution of assets raised is quite skewed; as can be seen from the Pareto chart below (Figure 1), the aggregate GAV rises quickly before tailing off.
Figure 1: Cumulative Distribution of Aggregate Assets Raised by US Third-Party Marketers
Source: 9AT
While it’s true that this pattern is reflective of competition dynamics, it is also due to functional specialisation within the fundraising ecosystem. Boutique placement agents tend to operate where the large, global platforms are either structurally less efficient or economically less incentivised to focus their efforts.
For emerging and mid-market managers in particular, fundraising is often less about broad global distribution and more about precision: identifying the right subset of institutional investors, crafting a tightly aligned narrative, and maintaining close, consistent (but not overbearing!) engagement throughout the process. In this context, smaller third-party marketers can offer a level of focus and responsiveness that is difficult to replicate at scale.
Boutique firms are also often more deeply embedded in specific strategies, geographies, or investor networks particularly private investors such as family offices, multi-family offices, HNWIs, etc., enabling them to access capital that can meet quicker, respond quicker, and write a check quicker.
As a result, while the Pareto distribution highlights a highly concentrated top end of the market, it also obscures the more nuanced reality that the long tail of third-party marketing support is structurally important, sustained by specialist intermediaries that play a critical role in connecting capital with emerging and niche investment strategies.
Within the cohort of advisors that use marketers, private equity leads the way, and by quite a way – 43.3% of all funds using a marketer are private equity funds. That’s almost double the second-placed category – hedge funds – with 3,4560 funds, or 22.3%.
Table 2: Preponderance of Advisor Category Using a Marketer
Category Funds Share Private Equity 6,696 43.3% Hedge Fund 3,450 22.3% Venture Capital 1,636 10.6% Other 1,599 10.3% Real Estate 1,081 7.0% Securitized Asset 984 6.4% Liquidity 35 0.2% Source: 9AT
Part of the reason would be that there are just more private equity funds that file to the EDGAR database. That in turn makes competition intense, and hiring dedicated expertise might be perceived as providing a capital raising edge. Plus, their larger size on average requires the target investor to be able to write a bigger check. That means less friends and family, more institutions, which is where placement agent relationships can shine.
Going back to the long tail shows us that for the 2,500 firms in our dataset, the 90th percentile is reached after only 423 firms, meaning that the remaining 2,077 support ‘just’ a couple of trillion dollars out of the $21.68trn total.
But those two trillion dollars are precisely where a) much of the innovation in private markets originates: first-time funds, specialist strategies, regional managers and emerging teams that collectively shape the next cycle of institutional allocation and b) niche capital raising relationships lie.
The majority of funds seem to be content with going down the DIY asset-raising route. But for those that aren’t – particularly new and emerging managers - there is clearly plenty of potential support out there.
Editor's Picks:
Here are a handful of articles that we’ve seen recently that we found interesting. Hopefully, you do, too!
- Hedge funds bet against European carmakers on Chinese competition fears
- Fewer LPs plan to increase allocations to private credit over next year
- Private equity bosses turn to carried interest loans as payouts stall
- Detroit Office CMBS: Limited Securitization, Divergent Credit Outcomes
- How to invest when everything is moving too fast
-
05/13/2026
What’s the Point of the Multiple Adviser Disclosure in Form ADV?
Form ADV, the disclosure document filed with the Securities and Exchanges Commission (SEC) by private fund advisers each year contains a treasure trove of information, and here at 9AT, one of our specialties is aggregating that data and formatting it so that it can be analysed and understood for our clients.
Most people focus on the obvious data points - assets under management, number of funds, fund category, etc. But there are plenty of others, including some that offer a window into the inner workings of an adviser, like the use of multiple investment advisers within a single private fund structure.
Section 7B of the ADV is where advisers provide information specific to each private fund to which they act as an adviser. Within this section, question 18 asks whether any investment advisers beyond those already disclosed elsewhere in the filing also advise the private fund in question. At first glance, this may appear to be nothing burger but in reality, it can provide meaningful insight into how a fund is managed, how responsibilities are allocated, and how the broader private funds market is evolving.
Many of the ‘other advisers’ listed on the form don’t provide significant insights - they’re simply subsidiaries of the parent adviser (think ‘Amazing Capital Management Europe’ being an ‘other adviser’ to ‘Amazing Capital Management 1 LP’, for example). In these cases, the arrangement is entirely routine and reflects the increasing complexity and specialization of modern private markets investing.
But some are more interesting. A multi-strategy hedge fund may allocate different portfolio sleeves to specialist external managers, for example. And a private equity platform may use separate advisory entities for deal origination, sector-specific expertise, or portfolio management functions. In each case, multiple advisers can help improve execution, deepen specialist knowledge, and broaden investment capabilities.
As a result, analyzing this field in the Form ADV has become increasingly valuable, particularly for investors and service providers.
For institutional investors and capital allocators, the presence of multiple advisers can offer insight not only into a manager’s investment model, but their operational model and governance framework as well. Investors conducting due diligence often want to understand precisely who exercises investment discretion, how decisions are made, and whether responsibilities are clearly delineated.
Obviously (you would hope obviously) that this comes up in due diligence meetings with the parent adviser. But while the use of multiple advisers may indicate a sophisticated and institutionalized platform, particularly in large or globally diversified advisers, on the flip side, it may introduce additional complexity around oversight, conflicts of interest, or fee structures, all important considerations for investors looking at placing capital.
For compliance professionals and regulators, the field helps identify how advisory functions are distributed across entities. The SEC has long focused on ensuring that advisers do not obscure control, avoid disclosure obligations, or create undisclosed conflicts through fragmented organizational structures and the information found in this field supports these goals.
The data is also increasingly useful for researchers and market analysts seeking to understand broader industry trends. Changes in the prevalence of multiple-adviser structures can reveal important shifts within the private funds market itself. One example of this is the hedge fund ‘pod shop’ concept. While most people know the brand names in the space, not all pod shops are the same; some don’t have any ‘other advisers’, so the fund is simply an aggregate of many internal portfolio managers, and some do. Data for Form ADVs filed in 2025 suggests that only 114 out of 1,798 hedge funds on the spreadsheet disclose “other managers” so it will be interesting to see if this increases over time.
The existence of multiple advisers should not automatically be interpreted as being either positive or negative. In many cases, it simply reflects the realities of modern private markets investing. The significance lies less in the structure itself and more in what the structure reveals about a fund’s operational approach, strategic ambitions, and governance framework.
But as the private funds industry continues to expand and diversify, operational transparency is growing in importance. The Form ADV is full of data that can offer a glimpse into the inner workings of a fund, and this is just one example.
Editor's Picks:
Here are a handful of articles that we’ve seen recently that we found interesting. Hopefully, you do, too!
-
04/08/2026
Slowing Pace of Auditor Change by US Private Funds but New Names Appear To Be Taking Share
Those of you who follow our blog will likely recall that in the past two Aprils, we have published an article that takes a look at how many private funds decided to raise something of a red flag in the previous year; namely, changing auditor.
We’re not in the business of disappointing our followers, so here we are with this year’s update!
Now that the end of the first quarter is in the books and all private funds will have filed their Form ADV for the prior year, we can crunch the numbers. And the ‘glass half full’ perspective is that there has been an improvement from last year.
In 2024 (specifically, Form ADVs filed in 2025), the category with the fewest auditor changes (as a percentage of the overall category) was venture capital, where only 1.9% of funds changed provider. But in the ‘other’ category, 4.7% of them did.
This year, the picture is a little different. Venture fell to 1.2% and Other to 2.7% and there were also falls in hedge funds and private equity (Figure 1 below).
Figure 1: Private Funds That Changed Auditor in 2024 and 2025, by Type
2024
2025
Fund Type # of Funds Changed - 2024 Total Funds - 2024 % Funds That Changed Auditor - 2024 # of Funds Changed - 2025 Total Funds – 2025 % Funds That Changed Auditor - 2025 Hedge Fund 611 17,550 3.5% 339 22,900 1.5% Other 491 10,477 4.7% 320 12,020 2.7% Private Equity 1,181 39,491 3.0% 1,325 47,635 2.8% Real Estate 269 7,367 3.7% 309 8,184 3.8% Venture Capital 642 33,085 1.9% 478 39,087 1.2% Source: 9AT
*Securitized Asset Funds and Liquidity Funds are excluded due to lack of statistical significance
The reasons why the numbers improved from last year are, admittedly, difficult to pin down with any certainty. But educated guesses would suggest that fund managers tend to stick to what they know in times of uncertainty and 2025 was indeed uncertain, both geopolitically and from a macroeconomic perspective.
Changing auditor does not necessarily have to be the red flag that it seems like on the surface – often the manager might change due to price, or a perceived better service offered by a different provider.
And there has been – is still – a human capital challenge in the audit industry more broadly which has had a secondary impact of making the larger firms more selective in terms of which clients they onboard.
Still, some change did happen, of course, and hidden among the data are some interesting titbits, as can be seen in Figure 2 below.
Figure 2: US Private Fund Auditor Changes, by Replacement Auditor, 2025
Rank Overall Hedge Fund Other Private Equity Real Estate Venture Capital 1 KPMG KPMG Grant Thornton Deloitte KPMG KPMG 2 Deloitte Eisner Amper KPMG PwC Ernst & Young RSM 3 PwC Ernst & Young PwC KPMG RSM BDO 4 Ernst & Young Aprio Deloitte BDO Citrin Cooperman Cohn Reznick 5 BDO Richey May Plante Moran Ernst & Young Deloitte Baker Tilly Source: 9AT
In 2024, across the five largest categories of funds available for selection on Form ADV, non-Big Four audit firms featured nine times out of 25. This past year, that number rose to 13, more than half.
The change is clearly most pronounced in venture capital, where only one of the Big Four featured in the top five of the competitor replacement lists. And that the Big Four hold the top spots in the overall rankings is influenced heavily by the private equity category, which is the only sub-category in which all four firms feature; three times as many PE funds changed auditor last year than venture capital funds, so the overall picture becomes a little distorted.
There is a long tail in the audit market. Some 56 firms replaced an incumbent in the hedge fund space last year; 41 did so in the Other category, 62 in private equity, 37 in real estate and 39 in venture.
That means plenty of choice for private fund managers who perhaps delayed making a change in 2025 due to the aforementioned market uncertainty.
We can’t end our annual auditor missive without looking at the new funds that were filed on this year’s Form ADV. It’s hard to knock out the big four when it comes to new funds – they take most of the top four spots in most of the categories.
But what’s interesting is to look at who takes up spots 5-10, as shown in Figure 3 below.
Figure 3: New Private Fund Auditor Hires in 2025, Places 5-10, ordered by fund count
Rank Overall Hedge Fund Other Private Equity Real Estate Venture Capital 5 BDO Cherry Bekaert Grant Thornton BDO Baker Tilly KPMG 6 Frank Rimerman Richey May EisnerAmper RSM MMB Baker Tilly 7 RSM EisnerAmper BDO Grant Thornton CohnReznick BDO 8 Baker Tilly BDO RSM Sanville RSM RSM 9 Grant Thornton RSM Baker Tilly CohnReznick BDO Weaver 10 EisnerAmper Grant Thornton CohnReznick EisnerAmper Cherry Bekaert Sensiba Source: 9AT
While there is one category where one of the big four has been displaced by the top four spots – Frank Rimerman taking first place in venture capital – there seems to be something of a consistency in the remainder of the top 10, with RSM and BDO featuring in all categories and Grant Thornton, EisnerAmper, and Baker Tilly each featuring in four categories.
Without going into detail, it’s worth noting that these rankings are done by fund count; ordering it by Total GAV serviced can (and does!) change the ranking and the overall picture. It’s also worth noting that these take into account funds from firms that filed ADVs in the first quarter of this year. While that represents ~80% of alternative fund advisers, the other ~20% that will file throughout the remainder of the year may change these rankings.
The geopolitical landscape is, let’s say, in the news at the moment. More so than ever, indeed. And while there tends to be a risk-off approach to investing during times of market dislocation, this mentality might be seeping into vendor selection as well.
Whether the percentage of funds that change auditor this year increases or whether they remain in ‘let’s not rock the boat’ mode remains to be seen but what is certain – as certain as can be, of course – is that here at 9AT, we’ll be watching, and we’ll do this again next April, at least!
Editor's Picks:
Here are a handful of articles that we’ve seen recently that we found interesting. Hopefully, you do, too!
- When Oil Becomes the ‘Main Character', These Hedge Fund Strategies Outperform
- Moody's cuts outlook on US BDCs to 'negative' on redemption pressure, rising leverage
- PE does not blink in the face of new market disruptions
- CMBS Delinquency Rate Jumps in March 2026, Led by Surge in Lodging Rate
- It’s not your imagination: AI seed startups are commanding higher valuations
-
03/09/2026
How Artificial Intelligence Is Reshaping Research in the Private Funds Market
Not a day goes by at the moment when the topic of artificial intelligence (AI) doesn’t come up in some industry, somewhere.
Much of the mass media coverage of the tool in recent weeks has swung towards the negative, whether that be because of its incorporation into military processes or because of its enormous potential to erase certain jobs.
We’re not here to make moral judgements, however. But we can speculate on how AI might influence the day-to-day of the private funds market, the space we call home, because we’re seeing it evolve in real-time.
And we think that those who adapt to change will be the ones best poised to win in this new paradigm.
AI and the Evolution of Data Collection, Verification, and Cleaning
One of the most significant challenges in private markets has always been data quality. Unlike public markets, where information is widely standardized and reported in real time, private funds data often originates from multiple sources, formats, and reporting conventions. As a result, collecting, verifying, and cleaning this information has historically required a significant amount of manual effort.
AI is beginning to automate many of these processes. Machine learning models can identify patterns across datasets, flag inconsistencies, and reconcile discrepancies far more quickly than a person can. And it doesn’t get tired, of course, so can do more work, quicker. Natural language processing can also extract relevant information from unstructured sources such as regulatory filings, investor reports, or news announcements.
The benefits to users are considerable. First, better automation improves data accuracy and consistency, which ultimately leads to more reliable analysis. Second, it significantly accelerates the speed at which new information becomes usable. Instead of waiting for sometimes lengthy manual validation processes, investment professionals can access cleaner, more up-to-date datasets.
AI as a Catalyst for Faster and More Sophisticated Development
AI is also transforming how data platforms themselves are built. Increasingly, AI tools are being used by development teams to write code, generate documentation, test functionality, and identify potential issues within software environments.
Yes, there are potential hazards – just ask Amazon. But these AI-assisted development workflows allow engineering teams to build, update, and expand platforms more rapidly. Tasks that once required significant manual coding effort can now be accelerated with the help of AI agents that assist with both development and testing.
For users, the benefits are both direct and indirect. Faster development cycles mean that platforms can evolve more quickly in response to user needs. New datasets can be integrated faster, features can be refined more frequently, and improvements can be deployed with greater consistency, which all leads to providing the user with a better product, faster.
AI as a New Way to Interact with Data and Software Platforms
The two aforementioned changes, while improving database and software products and services, are largely back-end ones.
But perhaps the most visible change AI is bringing and will continue to bring to the private funds industry is how users interact with data systems themselves. Traditionally, accessing information from a data platform required navigating menus, filtering columns, or downloading datasets for further analysis, whether that be in Microsoft Excel itself or by uploading the data into an entirely different system.
AI-powered interfaces are creating a far more intuitive experience. Instead of manually constructing searches, users can increasingly ask questions in natural language, much like interacting with a generative AI tool now.
We are already seeing the movement towards this new way of working in internet search. Last summer, an Adobe survey suggested that 77% of Americans use ChatGPT as a search engine.
This trend will continue. An allocator needing to research private credit might ask a platform to identify funds with specific return characteristics, geographic exposures, or vintage-year performance. A manager might request a list of allocators in a particular area when they are travelling in that area. Service providers will do the same. The system interprets the question, searches the relevant datasets, and delivers the answer in seconds.
This conversational interface significantly lowers the barrier to data analysis. Professionals who may not have deep technical expertise can still extract sophisticated insights from complex datasets. It also allows users to explore information more dynamically, refining questions and discovering insights in real time.
Conclusion
Artificial intelligence is rapidly becoming a foundational technology in how the private funds industry works with data and software. Its impact extends far beyond simple automation. From improving the quality of underlying datasets, to accelerating platform development, to transforming the way users engage with information, AI is reshaping the entire data ecosystem.
But these advances do not replace the expertise or judgment that investment professionals bring to the market. Instead, they enhance it by reducing the friction involved in collecting, analyzing, and exploring data.As adoption continues to grow, the firms that benefit most will be two-fold: Suppliers that view AI not simply as a tool to improve the back-end, but to provide their customers with a better way to access what they want; and customers that adopt products and services that are pushing the envelope in terms of moulding their offering to their customer base.
Editor's Picks:
Here are a handful of articles that we’ve seen recently that we found interesting. Hopefully, you do, too!
- Equity market is a paradise for stockpickers and hedge funds
- Rise of structured private credit transactions adds challenges for risk analysis
- Allocators Prefer the ‘Fluffy Airy’ Words of Private Equity to the Hard Math of Hedge Funds
- CRE CLO Issuance Surges to Start 2026, Putting 2021 Peak Levels Within Reach
- Investors spill what they aren’t looking for anymore in AI SaaS companies

